South Carolina hurricane deductible rules

When the hurricane deductible applies in South Carolina and what it can be, summarised from official state sources.

South Carolina in brief

South Carolina Regulation 69-56 limits a named storm deductible to a hurricane, tropical storm or tropical depression named by the National Weather Service or National Hurricane Center, and requires insurers to show a $100,000 worked example and a printed high out-of-pocket warning on any policy with a separate hurricane, named storm or wind/hail deductible.

Convert your percentage deductible to dollars →

What counts as a named storm

South Carolina Regulation 69-56 defines a named storm deductible as one triggered by a weather event named, designated or identified by the U.S. National Weather Service or the National Hurricane Center, and only a hurricane, tropical storm or tropical depression. A storm named by anyone else, including a winter storm named by the news media, cannot trigger it.

Disclosure on every policy

An insurer may not issue or renew a policy with a separate hurricane, named storm or wind/hail deductible unless it includes an example of how the deductible works on a policy valued at $100,000, with a clear explanation of the event that triggers it, and prints a warning on the policy face and declarations page that the deductible may result in high out-of-pocket expenses.

Adding or raising the deductible at renewal

An insurer may not add a hurricane, named storm or wind/hail deductible, or increase one, at renewal unless it provides the $100,000 example and the named insured signs or initials a disclosure acknowledging they have read it. The current version of the regulation took effect June 26, 2020.

What a 2% deductible costs

A percentage deductible is applied to the dwelling coverage limit (Coverage A), not to the damage. On $300,000 of dwelling coverage a 2% deductible is $6,000; on $500,000 it is $10,000. Covered storm damage below that amount is paid by the homeowner.
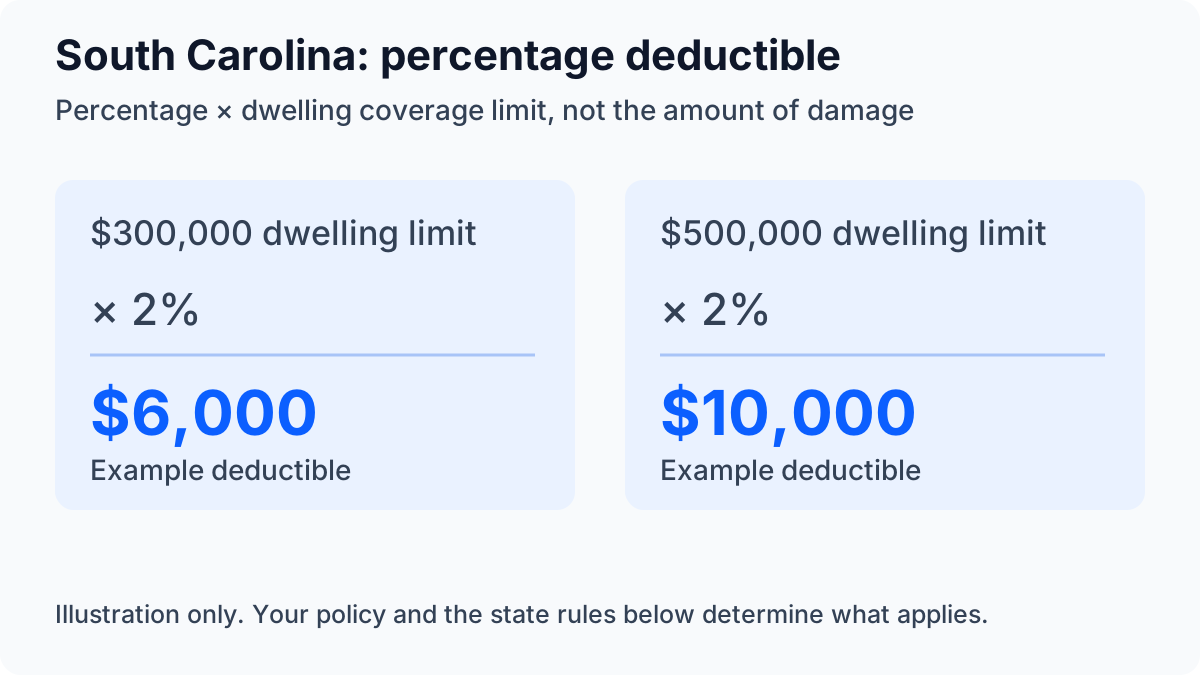
Example 2% deductible: $300,000 of dwelling coverage gives $6,000; $500,000 gives $10,000.
A visual summary of the examples below. The text, applicable periods, sources and limitations on this page govern.

Read your own declarations page and deductible endorsement: the policy wording, together with state law, decides which deductible applies to a loss. This page summarises the official state guidance only.

Frequently asked questions

Can a winter storm trigger a named storm deductible in South Carolina?

No. Regulation 69-56 limits a named storm deductible to a hurricane, tropical storm or tropical depression named by the National Weather Service or the National Hurricane Center. A winter storm or other event named by the news media cannot trigger it.

Does South Carolina cap hurricane deductible percentages?

Regulation 69-56 does not set a percentage cap. It requires disclosure instead: a $100,000 worked example, a printed warning on the policy face and declarations page, and a signed or initialed acknowledgement if the deductible is added or increased at renewal.

Hurricane deductible rules in other states

Florida · New York · Louisiana · Mississippi · Rhode Island · Maryland · Connecticut · North Carolina · New Jersey · Texas · Massachusetts

All states · Hurricane deductible calculator

Sources & further reading

Figures read from the official sources below and checked: October 21, 2026. Worked examples are our calculations, not benefit awards.